smooth in Python: TBATS implementation

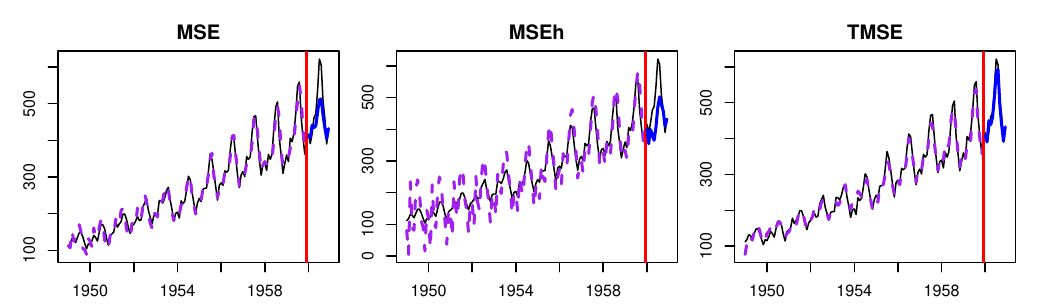
TBATS results on two datasets

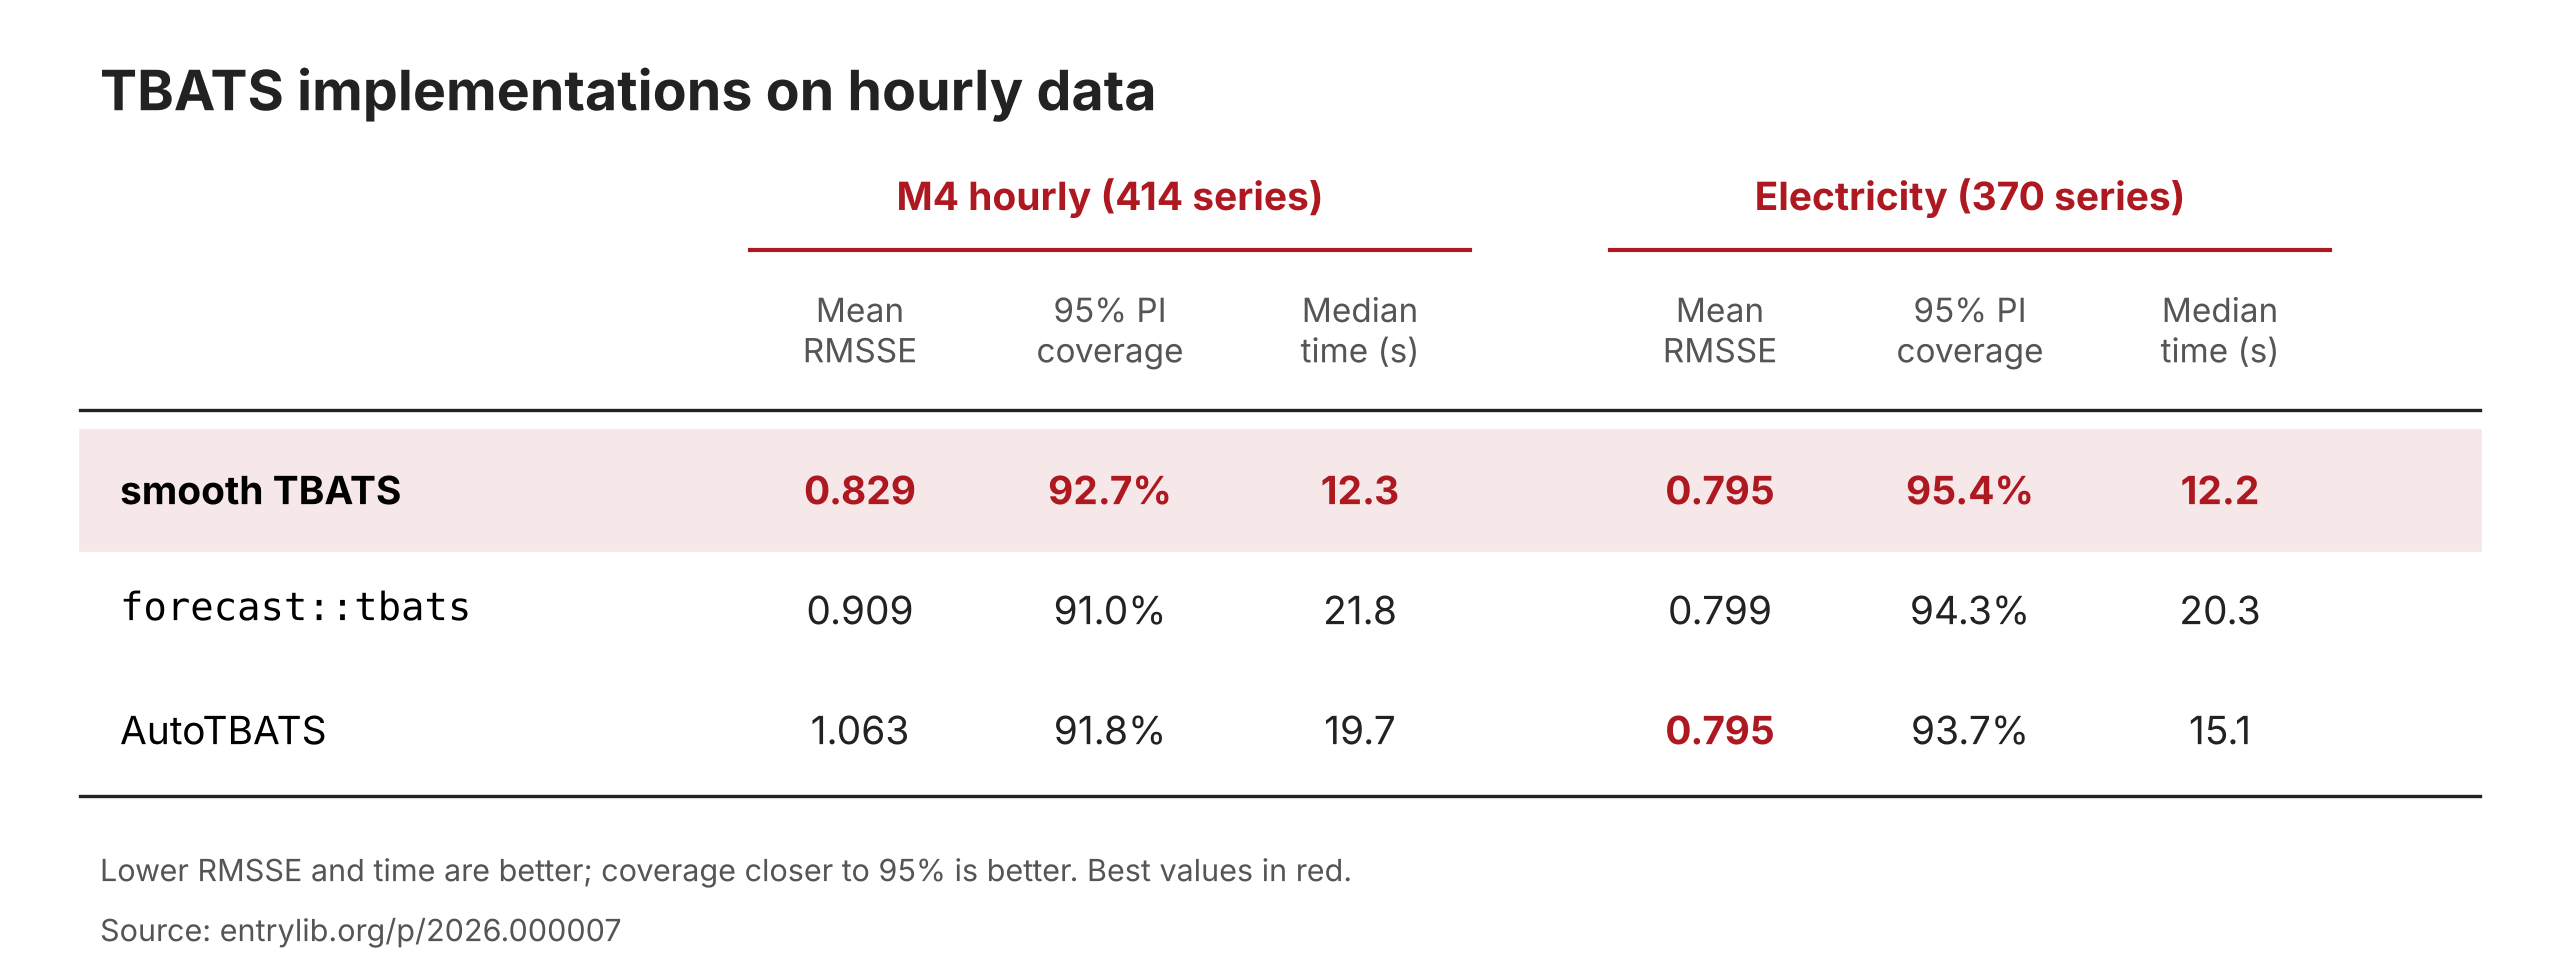
TBATS is a popular exponential smoothing model for data with complex seasonality: long seasonal periods, fractional ones (e.g. 52.18 weeks in a year, as I discussed in my previous post), and several of them at once. It models seasonality with harmonics and includes a Box-Cox transformation, ETS level and trend, and ARMA errors (De Livera, … Read more

smooth in Python: iETS and the Croston’s Method

Occurrence ETS model

Is there a statistical model underlying Croston’s method? This question has been bothering researchers for decades. Croston proposed his method back in 1972, and some even argued that there is no sensible model behind it (Shenstone & Hyndman, 2005). Yet there is one! Let me explain. But first, why bother? Because a method just gives … Read more

smooth in Python: fixed probability model for demand occurrence

Example of intermittent demand

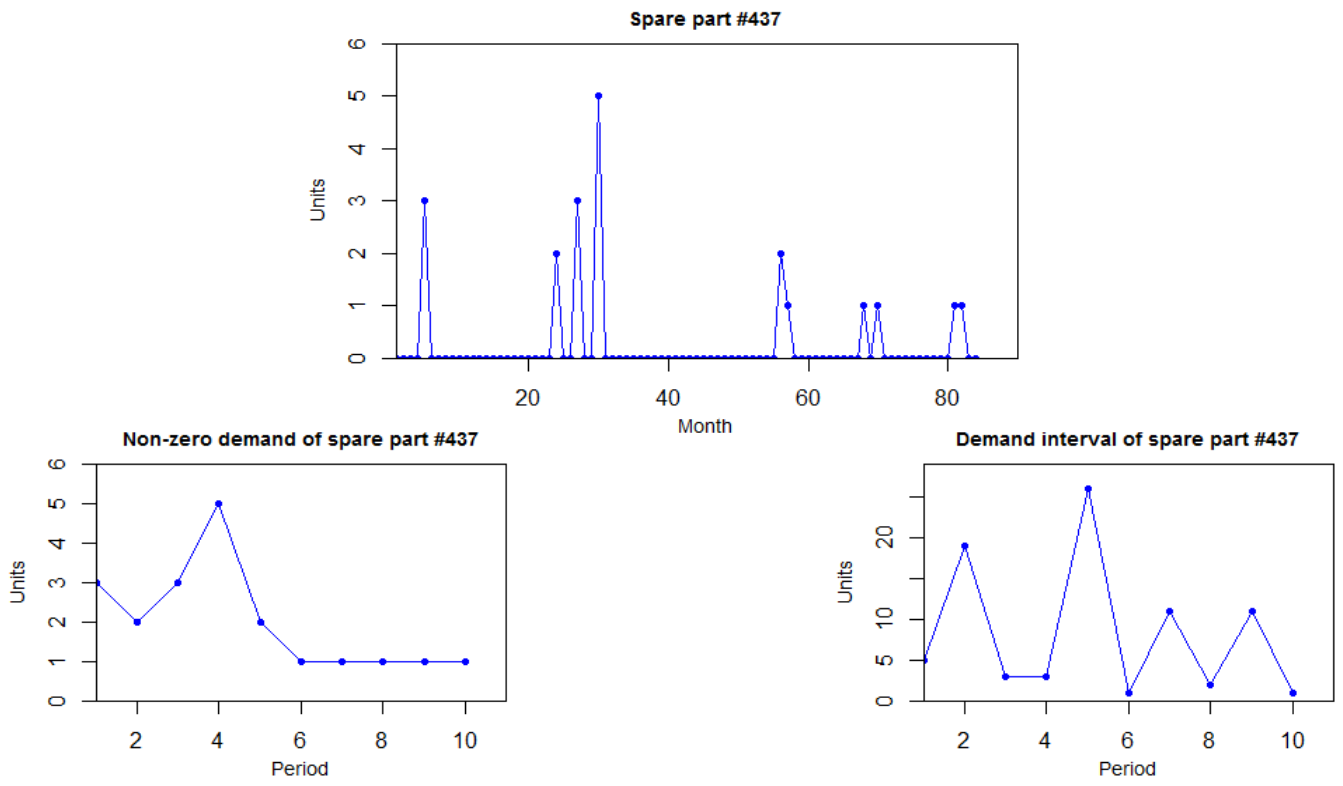
When demand is intermittent, one of the most useful forecasts you can produce is not “how much will we sell”, but “how likely are we to sell anything at all”. And this probability can be modelled, just like demand itself. This idea goes back to Croston, who suggested splitting intermittent demand into demand occurrence and … Read more

The main idea behind the Croston’s method

How Croston works

Have you heard of Croston’s method for intermittent demand forecasting? Some modern data scientists dislike it because it is too simple and not as accurate as some modern forecasting approaches. And they have a point. But here is why it is worth keeping Croston in mind. Back in 1972, John Croston, who worked on stock … Read more

Simple Exponential Smoothing: one parameter instead of many weights

SMA vs SES

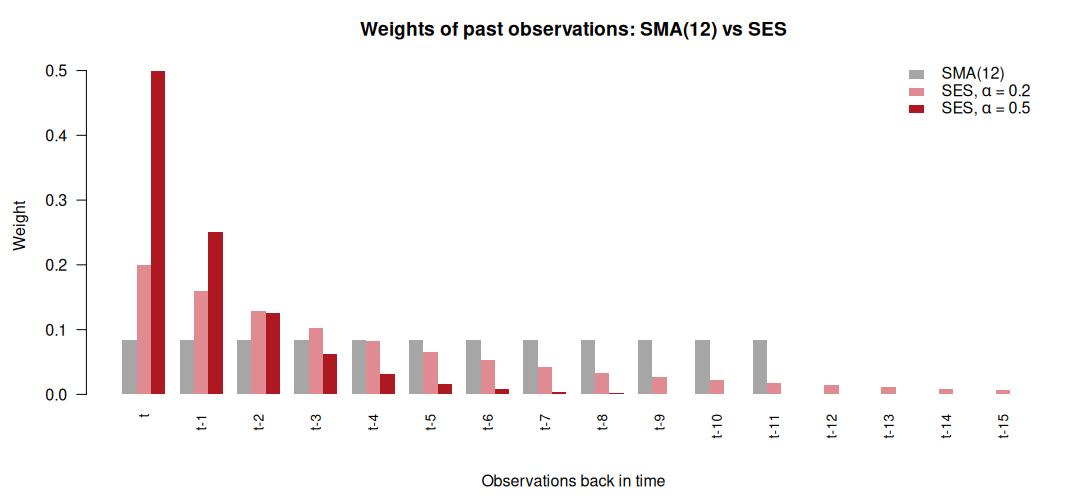
In one of the comments to my previous post about the Simple Moving Average on LinkedIn, a reader mentioned that they use a Weighted Moving Average with their own weighting scheme. This can work well although defining the weights can be a nuisance: a Weighted Moving Average of order 12 needs 12 weights that someone … Read more

smooth in python: Multistep losses

Example of fits of ETS with several multistep losses

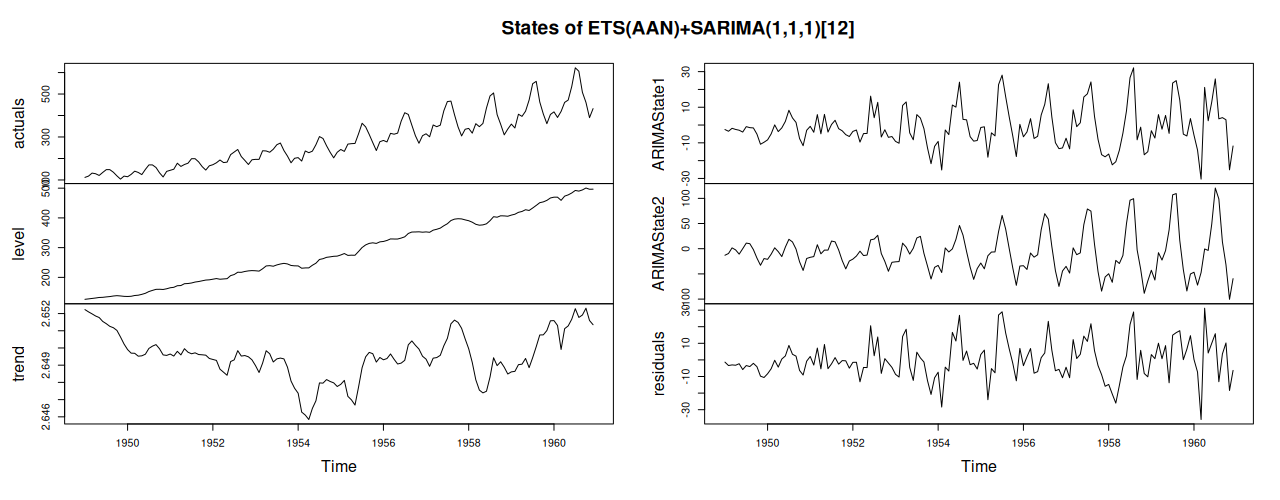
Why train a forecasting model on one-step-ahead errors when you care about 10-step-ahead accuracy? This is the core motivation behind multistep losses in dynamic models. This has connection with the so-called “direct forecasting strategy”. And here what it is and how to work with it in Python. Conventional maximum likelihood estimation minimises one-step-ahead errors. It … Read more

Demand Forecasting Principles course, October 2026

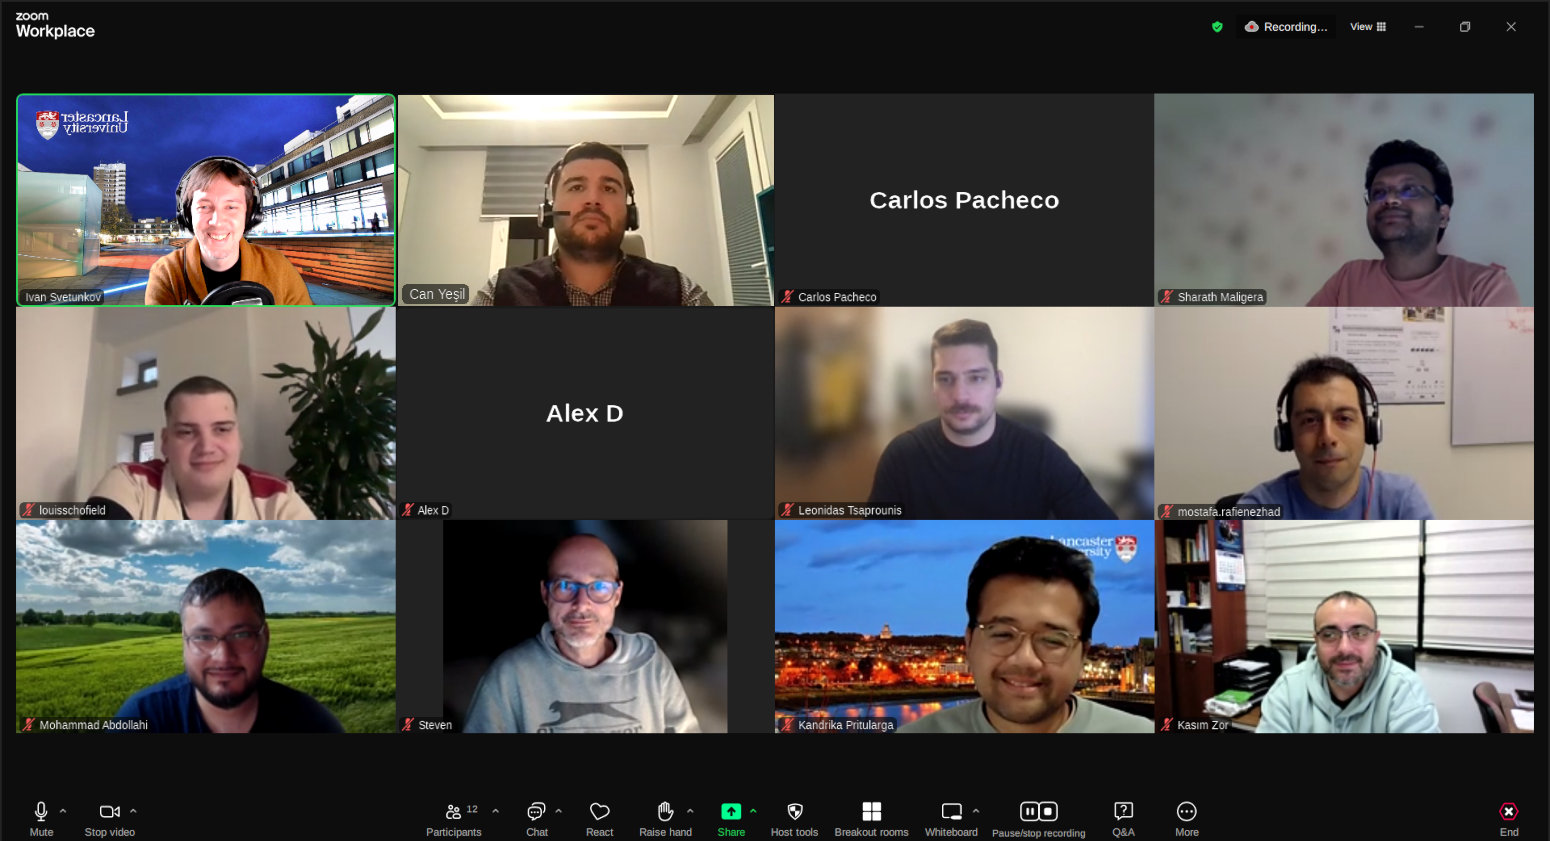
A photo of the participants of Demand Forecasting Principles open course

Our demand forecasting course is back! This time under the OpenForecast umbrella. Since 2024, Kandrika Pritularga and I have run a demand forecasting principles course at the Centre for Marketing Analytics and Forecasting. We ran it three times, and it has received good reviews from the participants. They liked that the material was motivated by … Read more

smooth in python: Non-normal distributions in ETS/ARIMA

So, you know quite well that the normal distribution is one of the most popular distributions in statistics. The reasons are manifold, including convenience for the academic community and the fact that it is taught in every single statistics course in the world. But what if we don’t want to be normal? There are situations … Read more

smooth in python: multiple seasonal ETS

Another interesting case in demand forecasting is the high frequency data. For example, if you work with demand on daily level, you might notice that demand increases every Monday but also exhibits proper seasonal fluctuations (e.g. decline every Winter). What do you do in this case? One of the solutions (old but gold) is the … Read more