smooth in Python: TBATS implementation

TBATS results on two datasets

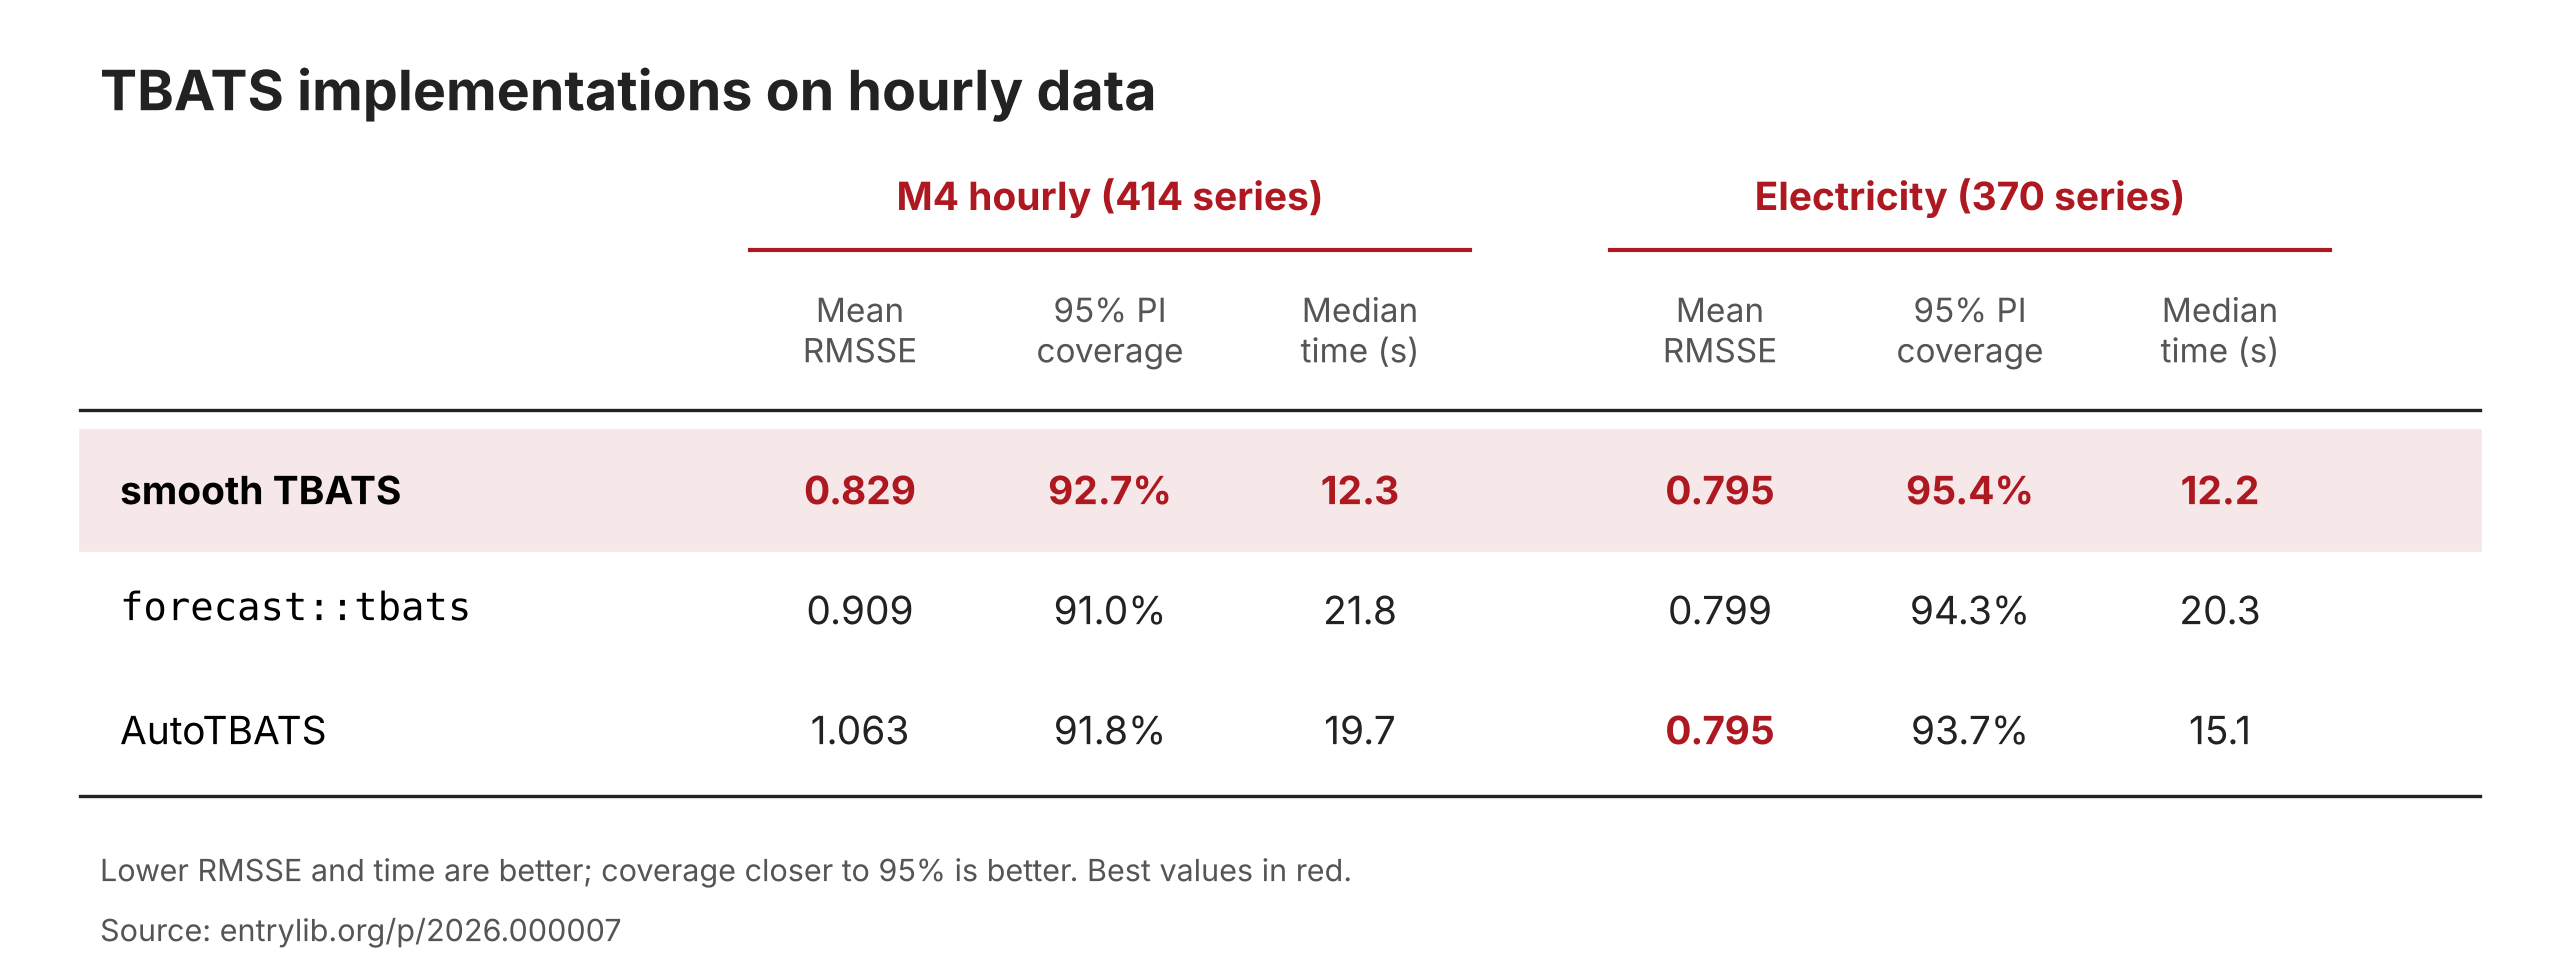
TBATS is a popular exponential smoothing model for data with complex seasonality: long seasonal periods, fractional ones (e.g. 52.18 weeks in a year, as I discussed in my previous post), and several of them at once. It models seasonality with harmonics and includes a Box-Cox transformation, ETS level and trend, and ARMA errors (De Livera, … Read more

smooth in Python: iETS and the Croston’s Method

Occurrence ETS model

Is there a statistical model underlying Croston’s method? This question has been bothering researchers for decades. Croston proposed his method back in 1972, and some even argued that there is no sensible model behind it (Shenstone & Hyndman, 2005). Yet there is one! Let me explain. But first, why bother? Because a method just gives … Read more

Simple Exponential Smoothing: one parameter instead of many weights

SMA vs SES

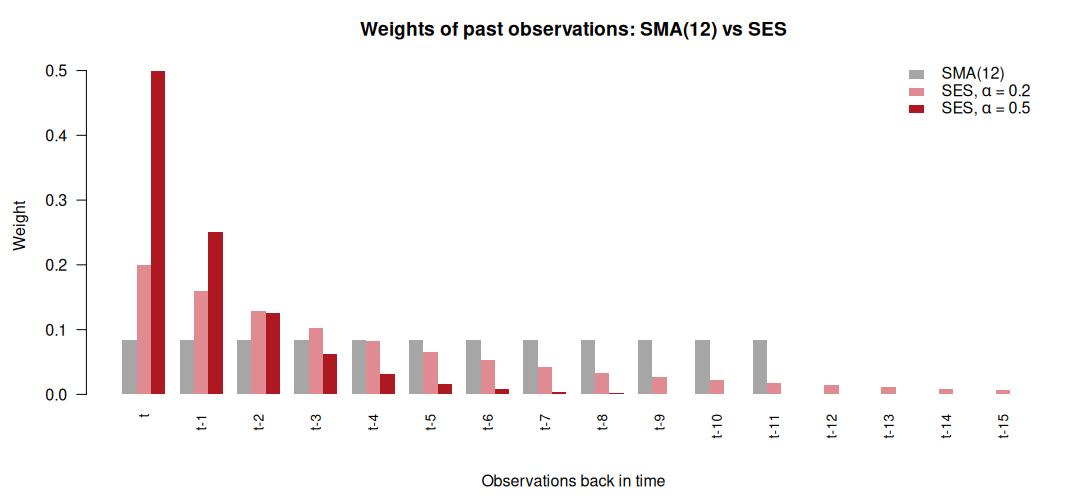
In one of the comments to my previous post about the Simple Moving Average on LinkedIn, a reader mentioned that they use a Weighted Moving Average with their own weighting scheme. This can work well although defining the weights can be a nuisance: a Weighted Moving Average of order 12 needs 12 weights that someone … Read more

smooth in python: Non-normal distributions in ETS/ARIMA

So, you know quite well that the normal distribution is one of the most popular distributions in statistics. The reasons are manifold, including convenience for the academic community and the fact that it is taught in every single statistics course in the world. But what if we don’t want to be normal? There are situations … Read more

smooth in python: multiple seasonal ETS

Another interesting case in demand forecasting is the high frequency data. For example, if you work with demand on daily level, you might notice that demand increases every Monday but also exhibits proper seasonal fluctuations (e.g. decline every Winter). What do you do in this case? One of the solutions (old but gold) is the … Read more

smooth in python: ETS with explanatory variables

We continue our series of posts on the functions from the smooth package for Python/R. Today we will see how to enhance your exponential smoothing with explanatory variables. What? Yes, you heard me! Let’s dive in! We all know that in real life sales don’t just evolve over time on their own. Any univariate model, … Read more

smooth in python: ETS forecast combination

Last time we saw how to do automated model selection using the ES function from the smooth package. Now I want to show how to produce combined forecasts from ETS. Why bother? There is a vast body of literature on forecast combinations (read this great review). The main idea is that you should not put … Read more

smooth in python: ETS with model selection

As some of you have heard, the smooth package is now on PyPI. So, I’ve decided to write a series of posts showcasing how some of its functions work. We start with the basics, ETS. ETS stands for the “Error-Trend-Seasonal” model or ExponenTial Smoothing. It is a statistical model that relies on time series decomposition … Read more

smooth forecasting with the smooth package in Python

Here is another piece of news I have been hoping to deliver for quite some time now (since January 2026 actually). We have finally created the first release of the smooth package for Python and it is available on PyPI! Anyone interested? Read more! On this page: Why does “smooth” exist? A bit of history … Read more