IIF Open Source Forecasting software workshop and smooth
Sticker of the smooth package for R

Here is one thing you have probably not heard of: a workshop on Open Source Forecasting software, held in Beijing on 26th – 27th June 2025. This was a closed event, with speakers attending by invitation only. It focused on recent advancements and potential avenues in open-source forecasting software. But why am I writing about … Read more
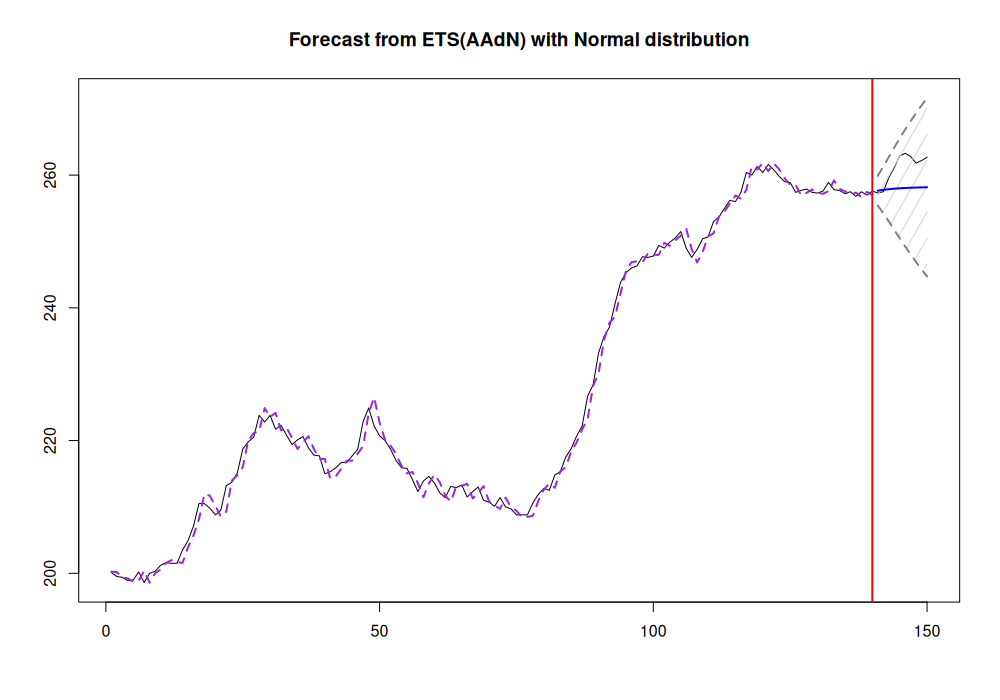
Methods for the smooth functions in R

Forecast from the full ADAM, containing both location and scale parts

I have been asked recently by a colleague of mine how to extract the variance from a model estimated using adam() function from the smooth package in R. The problem was that that person started reading the source code of the forecast.adam() and got lost between the lines (this happens to me as well sometimes). … Read more

Detecting patterns in white noise

Back in 2015, when I was working on my paper on Complex Exponential Smoothing, I conducted a simple simulation experiment to check how ARIMA and ETS select components/orders in time series. And I found something interesting… One of the important steps in forecasting with statistical models is identifying the existing structure. In the case of … Read more

smooth & greybox under LGPLv2.1

Good news, everyone! I’ve recently released major versions of my packages smooth and greybox, v4.0.0 and v2.0.0 respectively, on CRAN. Has something big happened? Yes and no. Let me explain. Starting from these versions, the packages will be licensed under LGPLv2.1 instead of the very restrictive GPLv2. This does not change anything to the everyday … Read more

smooth v3.2.0: what’s new?

smooth package has reached version 3.2.0 and is now on CRAN. While the version change from 3.1.7 to 3.2.0 looks small, this has introduced several substantial changes and represents a first step in moving to the new C++ code in the core of the functions. In this short post, I will outline the main new … Read more

Smooth forecasting with the smooth package in R

Authors: Ivan Svetunkov Abstract: There are many forecasting related packages in R with varied popularity, the most famous of all being forecast, which implements several important forecasting approaches, such as ARIMA, ETS, TBATS and others. However, the main issue with the existing functionality is the lack of flexibility for research purposes, when it comes to … Read more

The first draft of “Forecasting and Analytics with ADAM”

After working on this for more than a year, I have finally prepared the first draft of my online monograph “Forecasting and Analytics with ADAM“. This is a monograph on the model that unites ETS, ARIMA and regression and introduces advanced features in univariate modelling, including: ETS in a new State Space form; ARIMA in … Read more

After the creation of ADAM: smooth v3.1.0

Since the previous post on “The Creation of ADAM“, I had difficulties finding time to code anything, but I still managed to fix some bugs, implement a couple of features and make changes, important enough to call the next version of package smooth “3.1.0”. Here is what’s new: A new algorithm for ARIMA order selection … Read more

The creation of ADAM – next step in statistical forecasting

Good news everyone! The future of statistical forecasting is finally here :). Have you ever struggled with ETS and needed explanatory variables? Have you ever needed to unite ARIMA and ETS? Have you ever needed to deal with all those zeroes in the data? What about the data with multiple seasonalities? All of this and … Read more

Multiplicative State-Space Models for Intermittent Time Series, 2019

More than 2 years ago I published on this website a working paper entitled “Multiplicative State-Space Models for Intermittent Time Series“, written by John Boylan and I. This was an early version of the paper, which we submitted to International Journal of Forecasting on 31st January 2017. More than two years later (on 11th July … Read more