On differencing of ARIMA in state space

The model fit of MSARIMA

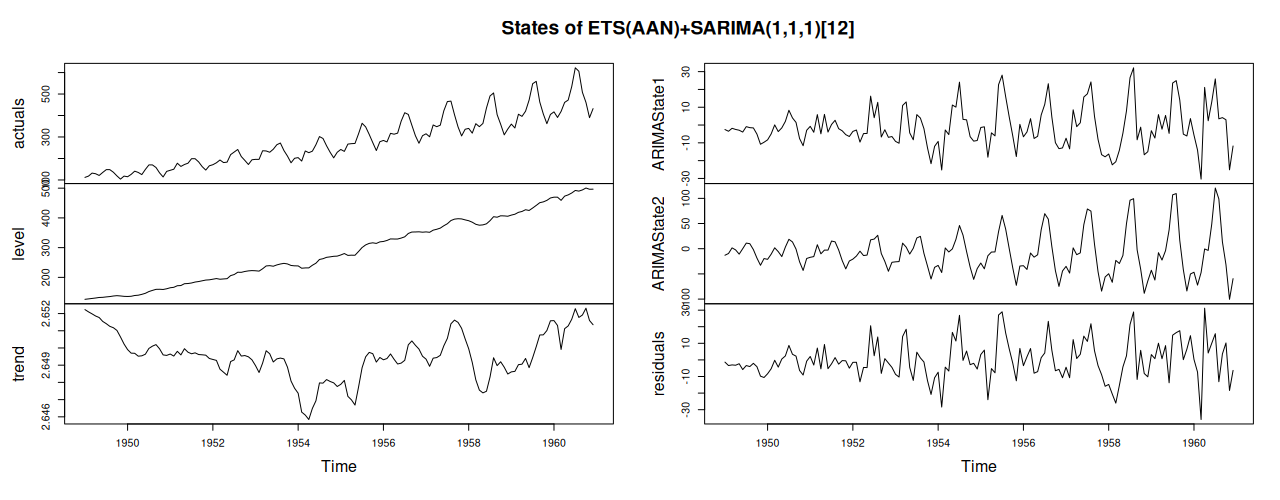
A reader left a comment under the MSARIMA post on LinkedIn saying that in order to compare ARIMAs via information criteria, we need to make sure that the candidate models have the same order of differencing. They are right — for the conventional ARIMA. BUT! In the state space formulation, the problem disappears. Here is … Read more

smooth in python: Multiple Seasonal ARIMA

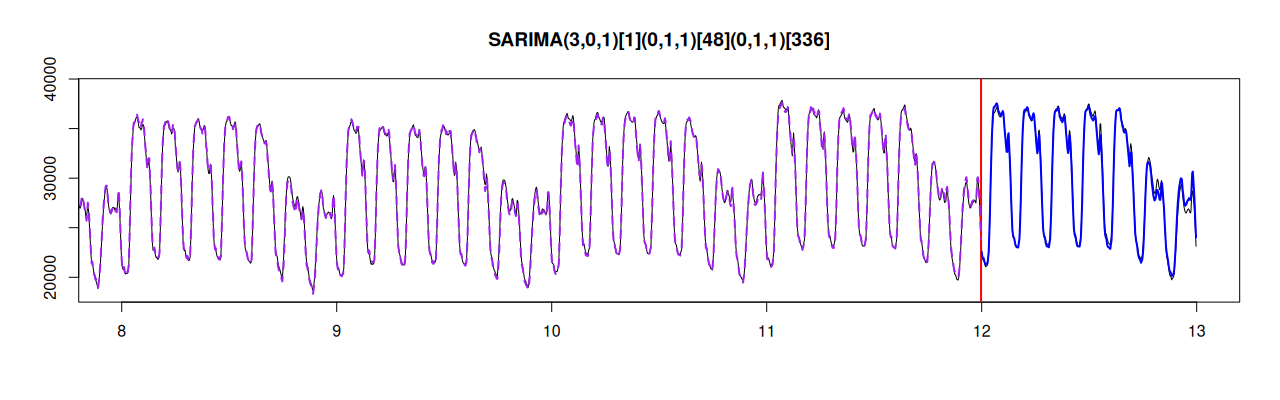
MSARIMA model fit and point forecast

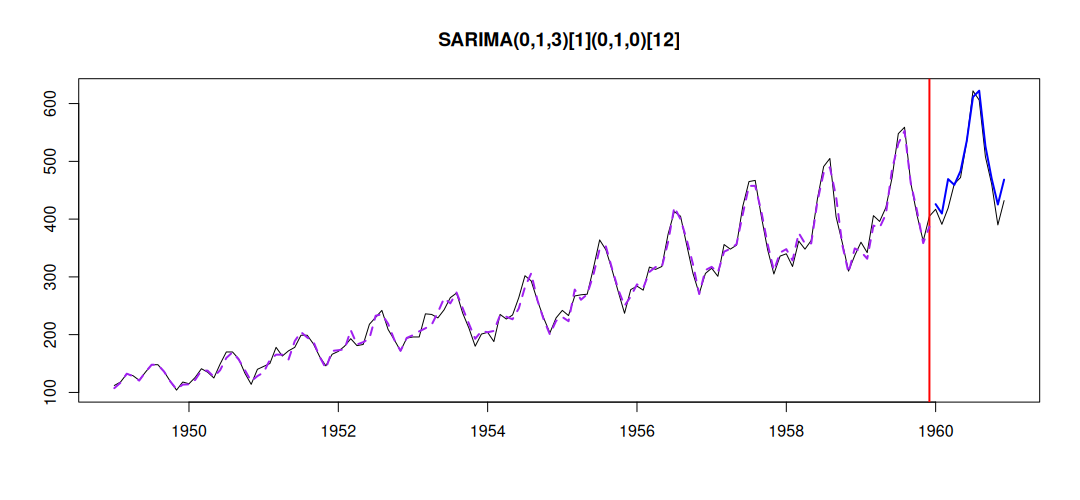
ARIMA has been a workhorse for decades. But the standard implementations quietly hard-code assumptions: one seasonal cycle, Gaussian errors, regressors handled separately etc. This is fine for textbook well-behaved data. But what do you do when you face real data? The conventional implementations (statsmodels or pmdarima in Python, stats in R) do their job well: … Read more

Fundamental Flaw of the Box-Jenkins Methodology

Sarah by Yegor Kamelev

If you have taken a course on forecasting or time series analysis, you’ve probably heard of ARIMA and the Box–Jenkins methodology. In my opinion, this methodology has a fundamental flaw and should not be used in practice. Here’s why. When Box and Jenkins wrote their book back in the 1960s, it was a very different … Read more

Detecting patterns in white noise

Back in 2015, when I was working on my paper on Complex Exponential Smoothing, I conducted a simple simulation experiment to check how ARIMA and ETS select components/orders in time series. And I found something interesting… One of the important steps in forecasting with statistical models is identifying the existing structure. In the case of … Read more

What’s wrong with ARIMA?

Have you heard of ARIMA? It is one of the benchmark forecasting models used in different academic experiments, although it is not always popular among practitioners. But why? What’s wrong with ARIMA? ARIMA has been a standard forecasting model in statistics for ages. It gained popularity with the famous Box & Jenkins (1970) book and … Read more

Multi-step Estimators and Shrinkage Effect in Time Series Models

Authors: Ivan Svetunkov, Nikos Kourentzes, Rebecca Killick Journal: Computational Statistics Abstract: Many modern statistical models are used for both insight and prediction when applied to data. When models are used for prediction one should optimise parameters through a prediction error loss function. Estimation methods based on multiple steps ahead forecast errors have been shown to … Read more

smooth v3.2.0: what’s new?

smooth package has reached version 3.2.0 and is now on CRAN. While the version change from 3.1.7 to 3.2.0 looks small, this has introduced several substantial changes and represents a first step in moving to the new C++ code in the core of the functions. In this short post, I will outline the main new … Read more

ISF2022: How to make ETS work with ARIMA

This time ISF took place in Oxford. I acted as a programme chair of the event and was quite busy with schedule and some other minor organisational things, but I still found time to present something new. Specifically, I talked about one specific part of ADAM, the part implementing ETS+ARIMA. The idea is that the … Read more

The first draft of “Forecasting and Analytics with ADAM”

After working on this for more than a year, I have finally prepared the first draft of my online monograph “Forecasting and Analytics with ADAM“. This is a monograph on the model that unites ETS, ARIMA and regression and introduces advanced features in univariate modelling, including: ETS in a new State Space form; ARIMA in … Read more